Unlocking Home Ownership: Discover the Benefits of a HomeReady Mortgage
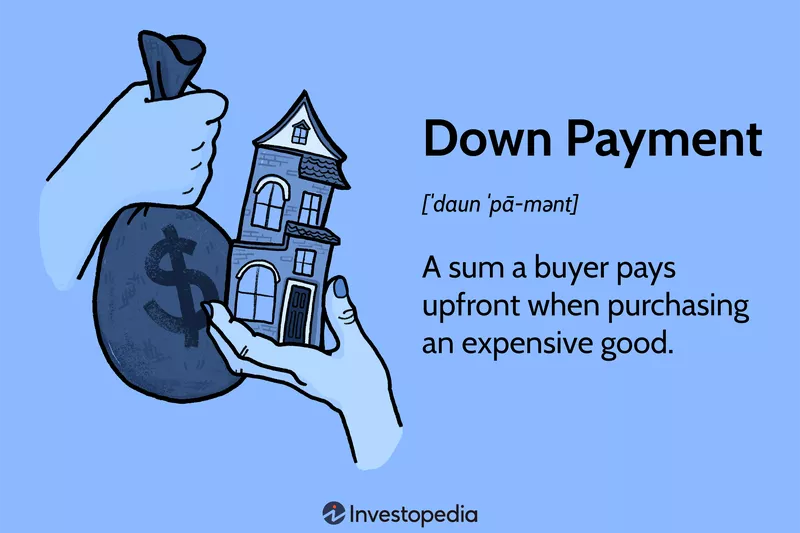
If you're a low to moderate income borrower with a solid credit history on the hunt for a new home, the HomeReady mortgage, backed by Fannie Mae, could be your gateway to homeownership. This unique mortgage option offers a significantly reduced down payment of just 3%, a considerable contrast to the traditional 20% required by most loans. Moreover, if you're looking to optimize your investment, the pricing for a HomeReady mortgage is either better than or competitive with standard mortgage rates.
Navigating the HomeReady Landscape
The HomeReady program welcomes both first-time and seasoned homebuyers, alongside those interested in refinancing an existing mortgage. To qualify, borrowers must have credit scores of at least 620; however, those with scores of 680 and above may benefit from even more favorable pricing. Additionally, HomeReady makes it more affordable by offering attractive mortgage insurance solutions.
Eligibility for this program entails having an income that is 80% or less of the area median income (AMI) based on the census tract of the property as of July 20, 2019. Notably, this includes properties located in low-income areas. Borrowers can have stakes in other properties; however, only one may be financed through a HomeReady mortgage when closing.
The Perks of Choosing HomeReady
The highlights of a HomeReady mortgage extend beyond the enticing 3% down payment. Borrowers can expect competitive pricing on loans, along with reduced mortgage insurance requirements when the loan-to-value (LTV) ratio falls between 90% and 97%. Homeowners can even eliminate monthly mortgage insurance when the LTV dips below 80%. What’s more, the program allows flexibility in funding sources for the down payment—donations, grants, and Community Seconds mortgages can be utilized.
Another boon for HomeReady borrowers lies in its adaptable terms. Although income restrictions apply, the mortgage doesn’t have to solely be in the name of those who will occupy the home. Family members, including parents, can act as co-borrowers, even if they're not moving in. Additionally, if the property has a rental unit, potential rental income can positively impact the borrower’s eligibility and improve their chances of securing a mortgage.
In a recent announcement, Fannie Mae revealed an exciting initiative for 2024. For borrowers with a total qualifying income not exceeding 50% of the area median, there’s a $2,500 credit available to assist with the 3% down payment requirement. This credit can be applied to loans finalized between March 1, 2024, and February 28, 2025.
Caveats of the HomeReady Program
That said, if the median home values in certain areas surpass the baseline limit by 115%, the loan ceiling could be elevated. Still, it’s vital to remember that just because you can secure a higher amount doesn’t mean you should; caution is advised when taking on debt that could prove unaffordable.
Additional Insights for Lenders and Borrowers
The HomeReady program also presents advantages for lenders. Fannie Mae’s Desktop Underwriter (DU) system automatically flags eligible loans while assessing credit risk. Lenders can gain risk-based pricing waivers for borrowers with credit scores exceeding 680 and LTV ratios above 80%. Furthermore, HomeReady loans can be integrated with standard loans featured in mortgage-backed security (MBS) pools and whole loan commitments.
Understanding the Financial Aspects
However, borrowers must be aware that mortgage insurance remains a requirement for those putting down less than 20%, and it will apply until the LTV ratio falls below the 80% mark.
The Bottom Line: A Gateway to Homeownership
The HomeReady mortgage program stands out as a beacon of hope for low-income borrowers aspiring to become homeowners. With an entry point as low as 3% for a down payment and a special $2,500 credit available for the lowest income earners, this initiative makes the dream of owning a home far more attainable. Notably, the program’s minimum credit score requirement is a mere 620, and it offers greater flexibility compared to conventional mortgage options when it comes to funding the down payment. Explore the possibilities and take a confident step towards owning your dream home!