Unlocking the American Dream: Affordable Paths to Homeownership
The aspiration of owning a home lies at the heart of the American dream, but with soaring housing costs and steep mortgage rates, many find their dreams slipping away. For those struggling with below-average incomes, the reality can feel daunting. However, there's hope! Thanks to various state and federal low-income mortgage programs, the door to homeownership is still ajar.
Government-Backed Mortgages: Your Ticket to Homeownership
The federal government has long been a key player in providing financial support for housing. After all, a secure living situation contributes to a stable and productive workforce. Programs managed by entities like the U.S. Department of Housing and Urban Development (HUD) and the Federal Housing Administration (FHA) are specifically designed to assist lower-income families in their quest for a home.
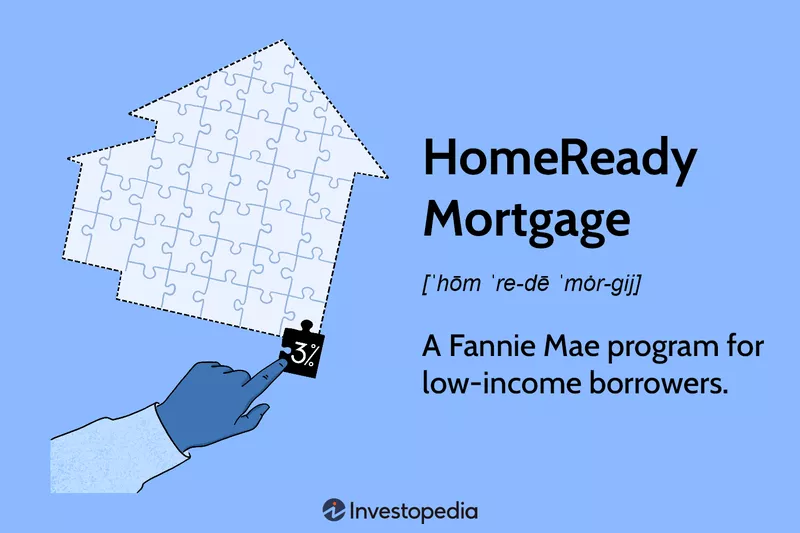
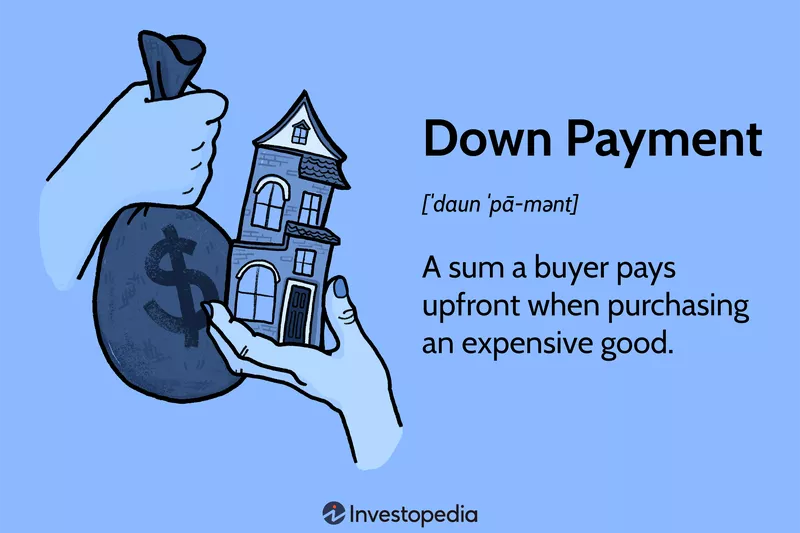
If you meet the eligibility criteria, you can access government-backed mortgage options with beneficial terms tailored to your needs. FHA loans, for example, are particularly aimed at first-time, low-income buyers, making it easier to step into the housing market. With a minimum credit score of 580 and a down payment of just 3.5%, these loans can make a world of difference.
Special Programs for Public Servants
Public service employees can rejoice! The HUD’s Good Neighbor Next Door program offers a remarkable 50% discount on home purchases for qualified buyers. To take advantage of this unique opportunity, you must work full-time in certain public service roles and buy a home in a designated revitalization area, committing to live there for at least three years. Keep in mind, properties under this program are available for a limited time—typically just seven days—so it’s crucial to be quick and prepared!
USDA Loans: Embracing Rural Living
For those considering life outside urban centers, the USDA Loan, also known as the Rural Development loan, allows eligible low-income families to buy homes with no down payment necessary. This option is restricted to specific rural locations, helping to promote housing in less populated areas. With 100% financing available, it’s a smart choice for those who qualify and are ready to make rural living their reality.
VA Loans: Honoring Our Veterans
Veterans and active military members, along with their families, have another avenue available through VA loans, provided by the U.S. Department of Veterans Affairs. These loans do not require a down payment, and sellers can assist in covering closing costs—making them an unbeatable option for those who have served. The eligibility varies based on the length of service, so it's essential to check the specific requirements related to your situation.
State-Specific Assistance Options
In addition to federal programs, all states and U.S. territories offer unique housing assistance tailored to local needs. Resources can differ significantly from one place to another, whether in the form of down payment assistance, grants, or forgivable loans. To discover what’s available in your state, be sure to explore your local HUD page and review the parameters of various programs before applying.
Defining Low Income: A Relative Concept
Understanding where you stand in relation to income thresholds is essential as you navigate homeownership options. The definition of low income varies widely, with distinct limits based on geographic location. For example, a family of four may be considered low-income in Jersey City, New Jersey, at an income of $107,000, while the same family in Jackson, Mississippi, may only require a yearly income of $66,800 according to HUD guidelines. This illustrates the importance of context when exploring housing assistance.
Buying Without a Down Payment: Is It Possible?
In today’s market, securing a home without a down payment is challenging but not impossible. Programs such as VA loans and USDA loans can provide the necessary support for eligible applicants. Generally, lenders expect a robust credit score—often in the high-600s—to qualify for these programs. However, the specific requirements may vary based on the lender and the type of financing sought.
Final Thoughts: Your Homeownership Journey Awaits
Achieving homeownership as a lower-income household is not an elusive dream. With the right knowledge and resources, you can explore various state and federal programs designed to ease this financial burden. Remember, what constitutes low income is relative to your region, so take the time to understand local guidelines and assess your eligibility to turn that dream into a reality.